Multiple Factors Drive Natural Rubber Rally(Sep 29)
Multiple Factors Drive Natural Rubber Rally
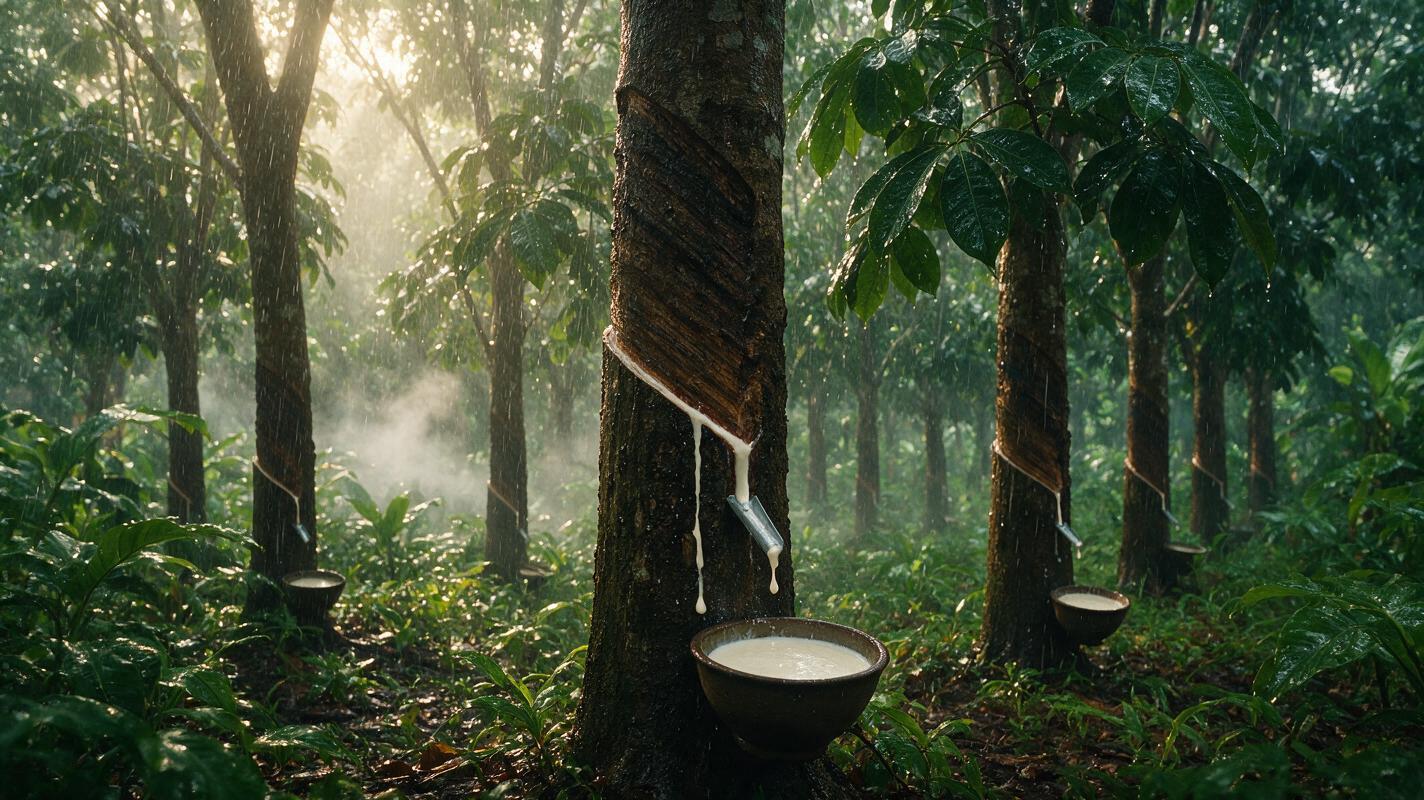
Last week, the natural rubber sector delivered a standout performance with a strong rally. The SHFE rubber main contract 2701 rose 4.53% for the week, closing at 19,600 yuan per ton. The TSR 20 main contract 2611 gained 6.98% for the week, closing at 17,100 yuan per ton, a record high since listing.
According to Ye Haiwen, Energy and Chemicals Research Manager at Guomao Futures, the price increase resulted from the convergence of multiple bullish factors. First, raw material latex prices remained firm, providing strong cost support. Heavy rainfall in southern Thailand continued to disrupt tapping, with cup lump purchase prices rising from 72.5 baht per kilogram at the start of the week to 76.5 baht per kilogram by the weekend, keeping latex prices above 80 baht per kilogram, a five-year high for the same period.
Second, El Nino-driven production cut expectations for the fourth quarter continue to intensify. The market is pricing in the risk of reduced supply from Southeast Asian producing regions in advance, pushing forward premiums wider. Third, warehouse receipts and inventory are both at low levels. As of September 24, TSR 20 warehouse receipt inventory was only 6,754 tons, down 4,233 tons week-on-week, the lowest in nearly four years. SHFE rubber warehouse receipts were approximately 148,000 tons, also at a historically low level. Domestic natural rubber social inventory continues to decline, with tight spot liquidity persisting.
Fourth, synthetic rubber price strength is driving substitution demand. Southwest Futures researcher Yang Xiya stated that the current rally is primarily supported by the supply side. Southeast Asian producing regions are in the peak production season, but recent excessive rainfall has repeatedly disrupted tapping and collection, keeping cup lump prices firm and providing solid cost support. Meanwhile, rising crude oil prices have driven synthetic rubber prices higher, making natural rubber's comparative advantage more prominent and increasing substitution purchases from downstream buyers.
On the demand side, all-steel tire operating rates are at 58.26% and semi-steel at 64.70%, maintaining a neutral level. Affected by weak terminal orders, profit pressure, and high finished goods inventory, tire manufacturers are largely purchasing on a just-in-time basis with limited willingness for high-price stockpiling. The traditional "Golden September" peak season has delivered mediocre results, with no substantive recovery in demand.
Looking ahead, Ye Haiwen maintains a bullish medium-to-long-term outlook. ANRPC cumulative production for the first seven months declined 1.18% year-on-year, with strong raw material cost support. El Nino has not yet significantly impacted actual production, with the reduction effect expected to concentrate in Q4 2026 to Q1 2027.
This platform focuses on the import and export of Chinese automotive equipment, gathering hundreds of certified Chinese automotive suppliers and connecting with global buyers. The platform achieves full transaction transparency, expands diverse cooperation opportunities, and helps both domestic and foreign parties build deep and stable cooperation bonds. Whether you are looking for vehicle manufacturers, purchasing automotive parts, or need customized procurement solutions, CNAUTO is your trusted first choice for cooperation.