Natural Rubber: Two‑Year High Triggers Tire Price Hikes(Sep 4)
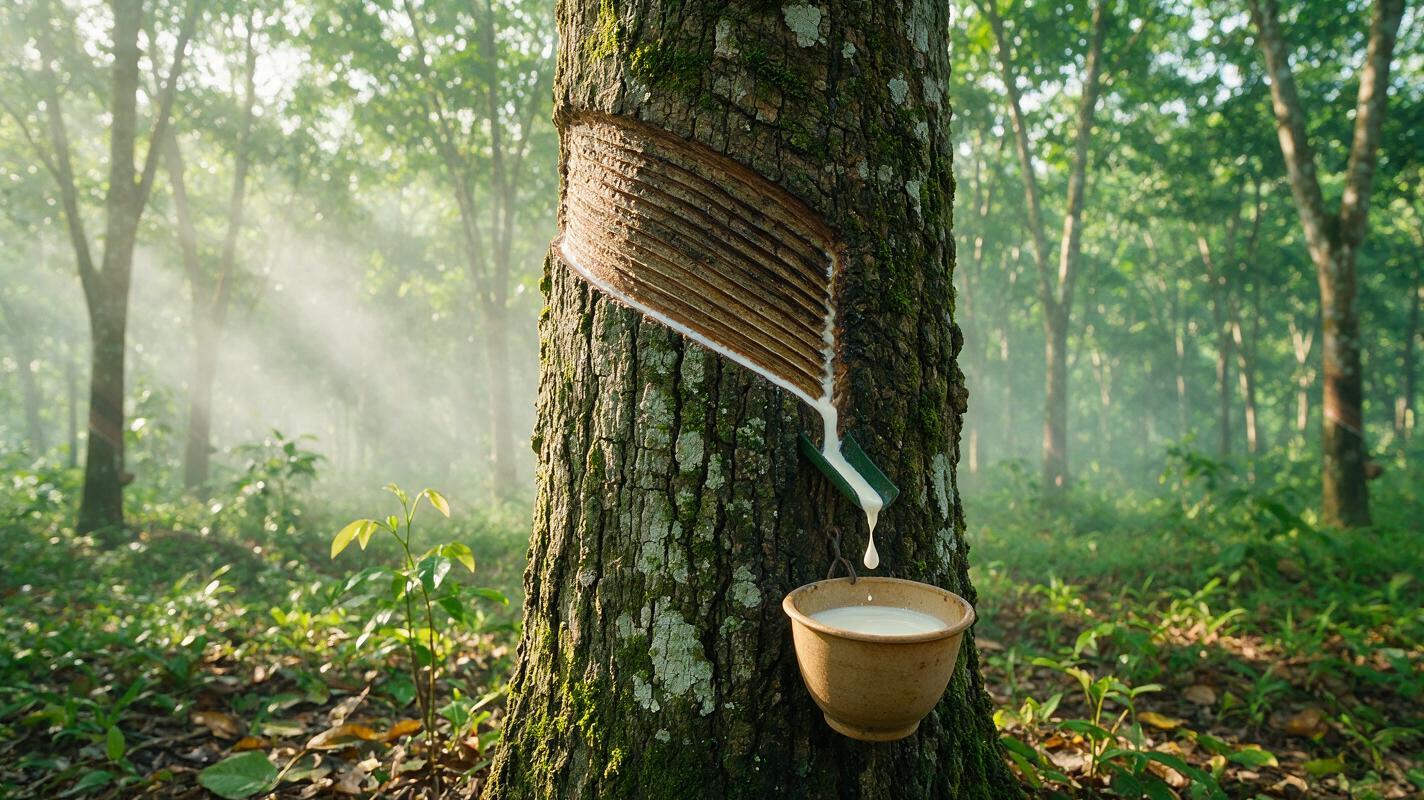
Since the second half of the year, the natural rubber market has maintained a strong trajectory. In early September, domestic natural rubber spot prices surpassed 17,900 yuan per ton, up approximately 14% from the beginning of the year, reaching a near two-year high. As of September 3, the SHFE rubber futures main contract briefly broke through 18,800 yuan per ton. Against the backdrop of continuously rising raw material costs, the downstream tire industry has set off a new wave of price increases, with listed companies showing divergent performance.
Rubber Price Surge
This round of rubber price increases is not driven by a single factor. The Association of Natural Rubber Producing Countries (ANRPC) forecasts that global natural rubber production in 2026 will be approximately 15.32 million tons, with consumption reaching 15.60 million tons, resulting in a supply-demand gap of approximately 280,000 tons, which has widened compared to 2025. On the supply side, aging rubber trees in Thailand, the spread of leaf fall disease in Indonesia, and declining production expectations in Vietnam, compounded by El Nino-induced drought in producing regions, have led to a clear supply contraction trend.
Meanwhile, due to geopolitical impacts, the synthetic rubber raw material butadiene is in tight supply with prices hitting historic highs, forcing downstream enterprises to shift toward natural rubber as a substitute, further pushing up natural rubber demand.
Cost Pressure Transmits to Downstream
Cost pressure has rapidly transmitted to the downstream of the industry chain. Since 2026, numerous tire companies including Michelin, Bridgestone, Zhongce Rubber, and Sailun Tire have密集 issued price increase notices, with increases generally ranging from 2% to 5%. Both foreign brands and domestic leaders have adjusted prices simultaneously, indicating that this round of cost pressure is industry-wide.
Zhongce Rubber stated in its price adjustment notice that the increase is still "far below the cost increase," and the company has launched futures hedging operations for natural rubber and synthetic rubber. Sailun Tire indicated that the company reduces procurement costs through strategic partnerships and long-term contracts with some raw material suppliers, while also adjusting procurement strategies and improving the accuracy of market forecasts. Additionally, the company mitigates the adverse impact of rising raw material prices by adjusting product prices and increasing the proportion of high-value-added tire sales.
Listed Companies Show Divergent Performance
Based on semi-annual reports disclosed by listed companies, the ability of each enterprise to withstand cost shocks varies significantly. Leading companies such as Zhongce Rubber and Sailun Tire achieved both volume and price growth in the first half of the year, while Linglong Tire and Qingdao Double Star continued to face pressure in their main businesses.
Rubber Prices to Maintain Firm Trend
Regarding the future trajectory of rubber prices, multiple brokerages and information agencies believe that the supply-demand tight balance will continue to support rubber prices remaining firm, though upside space is limited.
The latest monitoring by Shengyishe shows that natural rubber is currently in an "anti-decline warning" state, with bullish attributes prominent, but prices are already at a high range over the past year, with limited upside room, and caution is needed regarding high-level volatility risks.
Southwest Futures believes that natural rubber is currently in a game pattern of "strong expectations, weak reality." On the supply side, frequent rainfall during the peak production season has led to lower-than-expected raw material releases, and processing profits remain inverted, constraining production elasticity; the El Nino event has been confirmed with historically rare intensity, and production reduction expectations are the core narrative running through the second half and even into next year. On the demand side, tire operating rates are weak year-on-year, finished product inventory is high, and the peak season has yet to materialize in orders.
Guotai Junan Futures stated that cyclical production reductions in major producing regions determine that prices may initiate a long-term upward trend, expecting natural rubber to trend firmly with volatility in the second half. Industrial Futures believes that the 2026 natural rubber market will show characteristics of "rising center, amplified volatility." The long-term production capacity decline of global natural rubber has become a slow trend, but short-term elasticity remains; if heavy truck consumption growth is confirmed in the second half, rubber price upside elasticity will outperform 2025.
However, some institutions remain cautious about downstream profit recovery. China Tire Business Network analysis indicates that as new production capacity continues to be released on the supply side and international trade barriers further escalate, market competition will become more intense, and the overall industry profit recovery still faces significant uncertainty.
This platform focuses on the import and export of Chinese automotive equipment, gathering hundreds of certified Chinese automotive suppliers and connecting with global buyers. The platform achieves full transaction transparency, expands diverse cooperation opportunities, and helps both domestic and foreign parties build deep and stable cooperation bonds. Whether you are looking for vehicle manufacturers, purchasing automotive parts, or need customized procurement solutions, CNAUTO is your trusted first choice for cooperation.